The One, Big, Beautiful Bill Act (OBBBA) included provisions that many business owners and homeowners may have missed amid the headlines about tips and overtime: the accelerated termination of most clean energy tax credits. If you were counting on an electric vehicle credit, a solar installation credit, or a home energy-efficient upgrade credit, most of these windows have already closed. Here is what ended, what is still open, and what to do now.
Electric Vehicle Tax Credits: Ended September 30, 2025
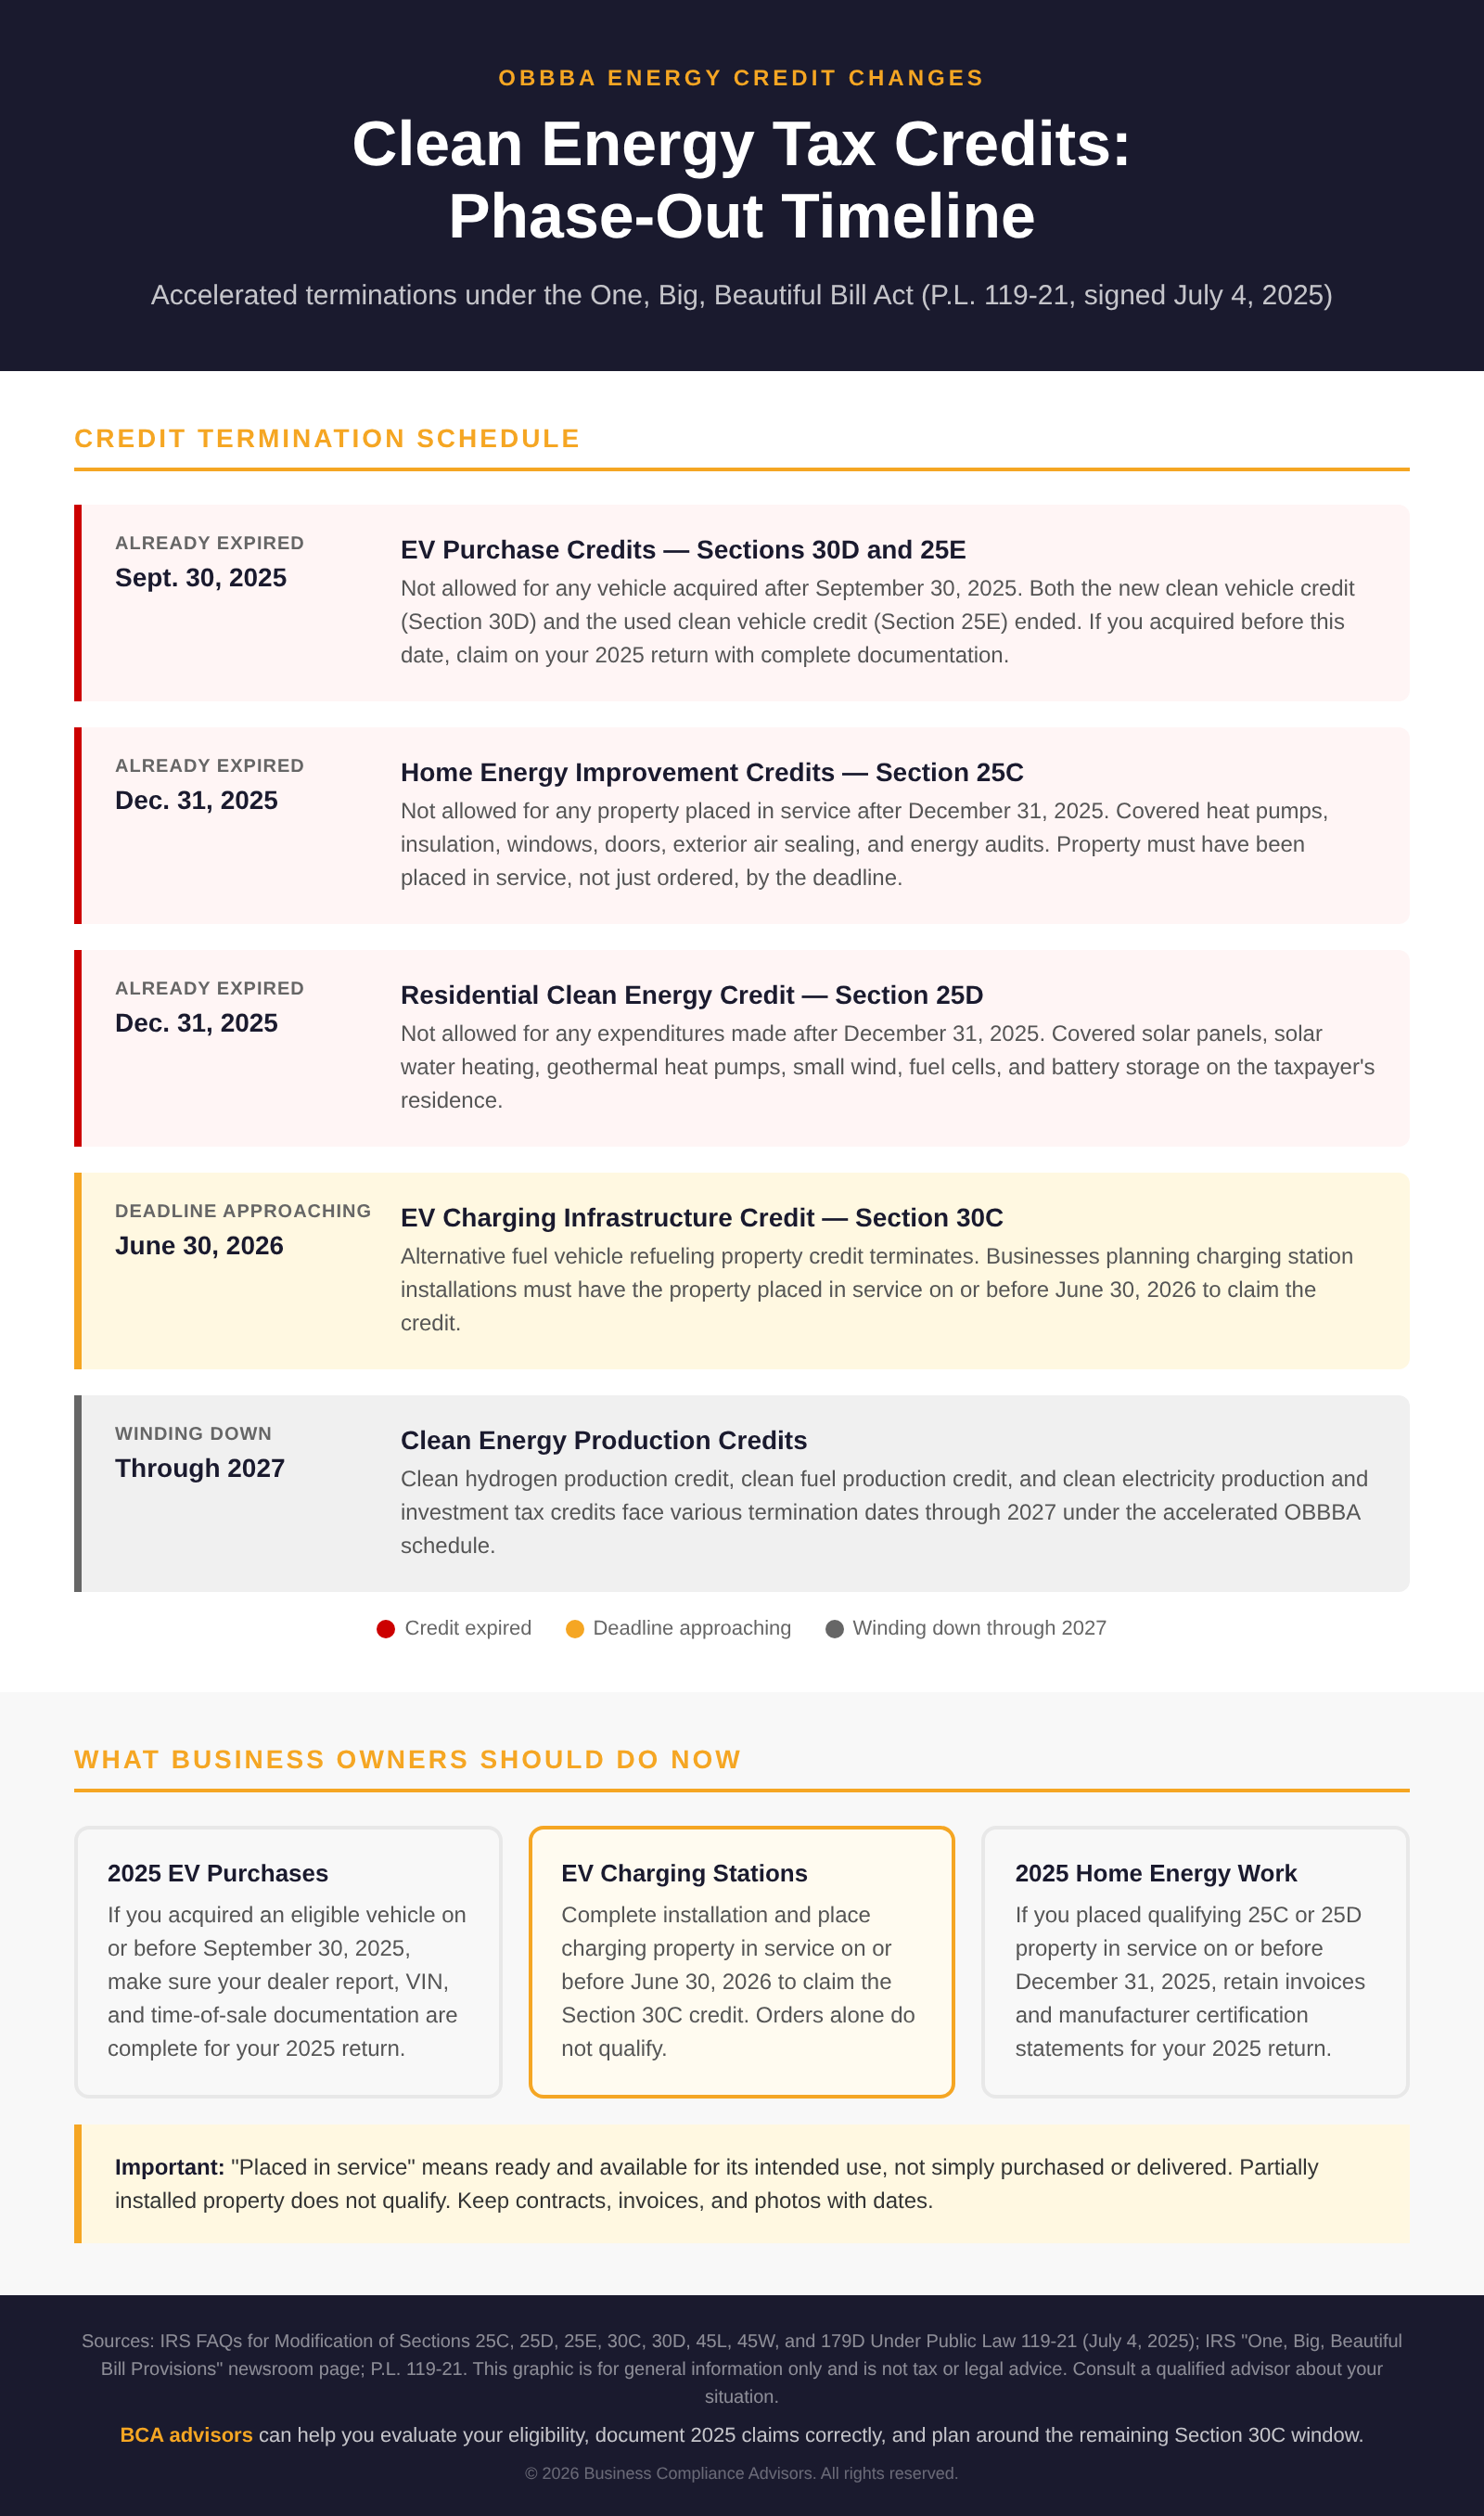
The new clean vehicle credit (Section 30D) and the previously owned clean vehicle credit (Section 25E) are not allowed for any vehicle acquired after September 30, 2025. If you acquired an eligible vehicle on or before that date, you can still claim the credit on your 2025 return, provided you have the dealer time-of-sale report, VIN, and other required documentation.
Home Energy Improvement Credit: Ended December 31, 2025
The energy-efficient home improvement credit (Section 25C), which covered heat pumps, insulation, windows, doors, exterior air sealing, and home energy audits, is not allowed for any property placed in service after December 31, 2025. “Placed in service” means ready and available for its intended use, not simply ordered or delivered. If you completed qualifying work in 2025, keep invoices, manufacturer certification statements, and proof of installation date for your 2025 return.
Residential Clean Energy Credit: Ended December 31, 2025
The residential clean energy credit (Section 25D), which covered rooftop solar, solar water heating, geothermal heat pumps, small wind, fuel cells, and battery storage on a taxpayer’s residence, is not allowed for expenditures made after December 31, 2025. Unlike 25C, the 25D rule looks at when the expenditure was made. If you signed a contract and paid a deposit before year-end but the system was not placed in service until 2026, consult your tax advisor about whether the expenditure date supports a 2025 claim.
EV Charging Infrastructure: Deadline June 30, 2026
The alternative fuel vehicle refueling property credit (Section 30C), which covers EV charging stations and other alternative fuel infrastructure, terminates for property placed in service after June 30, 2026. This is the one remaining window. If you are a business owner planning to install charging stations, the property must actually be placed in service on or before June 30, 2026 to claim the credit. Orders, deposits, and partial installations do not qualify.
Clean Energy Production Credits: Winding Down Through 2027
For businesses involved in clean energy production, the clean hydrogen production credit, the clean fuel production credit, and the clean electricity production and investment tax credits face various termination dates through 2027 under the accelerated OBBBA schedule. If your business model depends on these credits, consult with your tax advisor about the specific phase-out applicable to your operations and projects already underway.
What Business Owners Should Do Now
If you placed qualifying 25C or 25D property in service, or acquired an eligible EV, on or before the relevant 2025 deadline, make sure documentation is in order for your 2025 return. If you are planning EV charging infrastructure, the Section 30C window closes June 30, 2026, and the property must be placed in service by that date. The broader policy shift away from clean energy incentives should also factor into long-term capital planning if your business model assumed these credits would continue.
Disclaimer: This article is for informational purposes only and is not legal, tax, or financial advice. BCA is not a licensed professional services firm. We help clients assess their situations and work with licensed attorneys, tax advisors, and other qualified professionals on your behalf. Read our full Terms and Conditions. Have questions? Contact BCA and let us put the right team together for you.
Sources and Further Reading
- P.L. 119-21 (One, Big, Beautiful Bill Act), Sections affecting IRC 25C, 25D, 25E, 30C, 30D, 45L, 45W, and 179D
- IRS FAQs for Modification of Sections 25C, 25D, 25E, 30C, 30D, 45L, 45W, and 179D Under Public Law 119-21: irs.gov/newsroom/one-big-beautiful-bill-provisions
- IRS Clean Vehicle Credits: irs.gov/credits-deductions/credits-for-new-clean-vehicles-purchased-in-2023-or-after